FTSE Trims Early Rally to Close Near Flat, First Monthly Gain in Three Months
FTSE Trims Early Rally to Close Near Flat, First Monthly Gain in Three Months
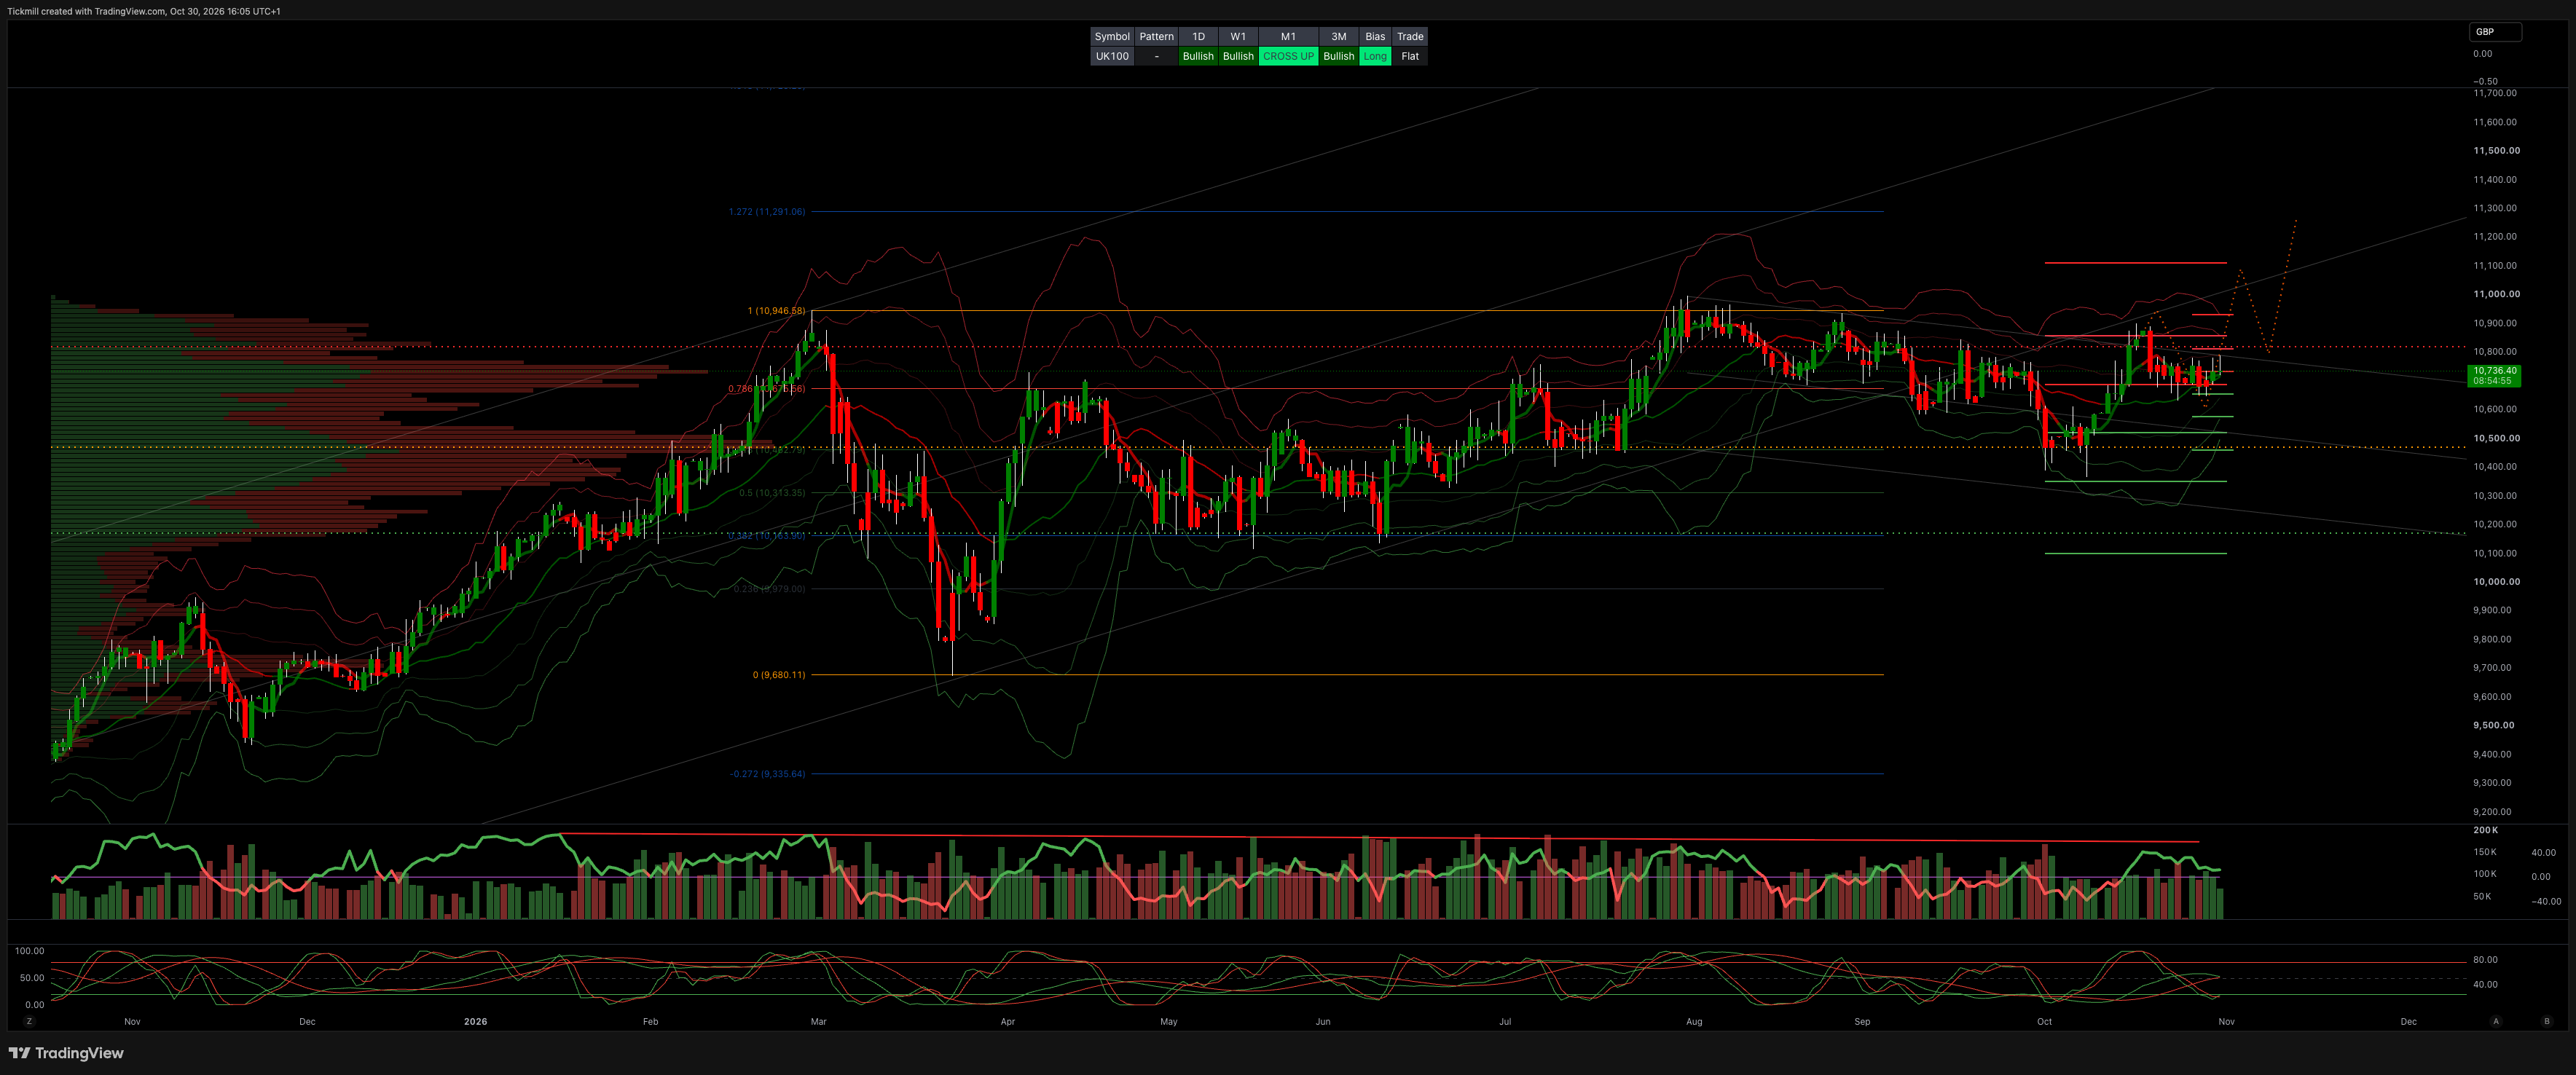
London's benchmark FTSE 100 gave up the bulk of its early morning gains on Friday to close near the flat line. An initial rally—driven by blockbuster quarterly earnings from AstraZeneca and BP, paired with continued relief over Chancellor John Healey’s less punitive budget tax measures—gradually faded as sharp declines across domestic banking heavyweights and mining stocks weighed on sentiment. Despite the late-session pullback, the blue-chip index successfully locked in its first positive monthly performance in three months.
Pharmaceutical and telecommunications heavyweights spearheaded top-flight risers. AstraZeneca jumped 4% after third-quarter earnings beat market forecasts, reporting profit attributable to shareholders of $3.12 billion (diluted EPS of $2.00 vs. $1.62 prior year) and reaffirming its full-year guidance. Peer GSK advanced 2.3%, while BT Group surged more than 5% to lead blue chips on reports of expanding network commercial agreements. Robust demand across defensive consumer, media, and business services lifted Prudential, RELX, Experian, WPP, Coca-Cola Europacific Partners, Reckitt Benckiser, Unilever, and Haleon by 2% to 3%. Solid gains between 1.0% and 1.8% were logged across Diageo, Marks & Spencer, Croda International, J Sainsbury, Admiral Group, Rentokil Initial, Imperial Brands, Coca-Cola HBC, Tesco, Associated British Foods, Kingfisher, The Sage Group, and Bunzl. In the energy patch, BP edged up 0.6% after reporting quarterly profits of $8.46 billion, well ahead of consensus estimates due to robust refining margins.
Conversely, domestic lenders and mining names severely restricted broader upside. NatWest Group tumbled 7.3% to lead decliners, as an underlying miss on net interest income overshadowed an operating profit beat and reaffirmed full-year targets. Sector peer Lloyds Banking Group dropped 3.1%. Natural resource stocks faced broad selling pressure amid softening metals prices, with precious metal miner Fresnillo dropping 4.1%, copper producer Antofagasta losing 4.0%, and Endeavour Mining sliding 3.4%. Technology and telecom shares also dragged, with Airtel Africa shedding 4.5%, Polar Capital Technology Trust sliding 4.3%, and Computacenter dropping 3.4%.
On the domestic macroeconomic front, Nationwide Building Society reported that U.K. house price growth stalled month-on-month in October 2026 (0.0%), defying consensus expectations for a 0.1% decline and improving on September's revised 0.3% drop. The stabilization in housing valuations provided evidence of consumer resilience despite elevated mortgage rates and ongoing fiscal uncertainty.
As we look ahead to the upcoming week, market watchers are gearing up for a challenging economic landscape. The Bank of England is anticipated to implement a 25 basis point interest rate increase on Thursday, spurred by robust UK employment figures, steady services inflation at 3.7%, and a solid composite PMI. Meanwhile, attention in the US will be on Tuesday's midterm elections, along with a packed schedule of employment data—featuring job openings, the ADP report, and the highly anticipated non-farm payrolls on Friday. All eyes will be on these indicators to see if the ongoing growth supports a potential interest rate hike from the Federal Reserve in December.
Finish Line: London equities closed a volatile week and month on a resilient note, holding onto modest gains to secure a positive October finish. While bank earnings friction and mining weakness eroded intraday momentum, stellar quarterly updates from AstraZeneca and BP alongside steady domestic housing metrics kept the benchmark anchored above key structural support.
Disclaimer: The material provided is for information purposes only and should not be considered as investment advice. The views, information, or opinions expressed in the text belong solely to the author, and not to the author’s employer, organization, committee or other group or individual or company.
Past performance is not indicative of future results.
High Risk Warning: CFDs are complex instruments and come with a high risk of losing money rapidly due to leverage. 68% and 74% of retail investor accounts lose money when trading CFDs with Tickmill UK Ltd and Tickmill Europe Ltd respectively. You should consider whether you understand how CFDs work and whether you can afford to take the high risk of losing your money.
Futures and Options: Trading futures and options on margin carries a high degree of risk and may result in losses exceeding your initial investment. These products are not suitable for all investors. Ensure you fully understand the risks and take appropriate care to manage your risk.
Patrick has been involved in the financial markets for well over a decade as a self-educated professional trader and money manager. Flitting between the roles of market commentator, analyst and mentor, Patrick has improved the technical skills and psychological stance of literally hundreds of traders – coaching them to become savvy market operators!